When Tapping Home Equity in Retirement Makes Sense Despite the Risks
Financial expert Dave Ramsey typically discourages borrowing against your home, but utilizing home equity can sometimes assist retirees facing financial strain. Understanding the differences between reverse mortgages and HELOCs helps homeowners weigh the risks of using property as collateral.
 🏠Mortgages & Housing
Photo: Money.com
Key points
- Dave Ramsey generally advises against taking on debt or reverse mortgages in retirement.
- Tapping home equity can help cover bills or consolidate high-interest credit card debt.
- Homeowners risk foreclosure and must continue paying property taxes and insurance.
Personal finance personality Dave Ramsey maintains a strict stance against debt, frequently advising homeowners to eliminate their mortgages entirely and avoid reverse mortgages or home equity loans during retirement. Despite this guidance, unexpected financial pressures can arise when retirement savings fall short, leaving older adults with significant property value but limited liquid cash.
While Ramsey cautions that reverse mortgages recreate debt after years of repayment, utilizing home equity can sometimes serve a practical purpose. Borrowers might use these funds to manage necessary living expenses or consolidate high-interest obligations such as credit card debt. Options range from Home Equity Conversion Mortgages, which require homeowners to be at least 62 years old, to home equity lines of credit that do not have the same age requirement.
- Avoid using home equity loans or HELOCs for discretionary expenses like vacations.
- Weigh the danger of foreclosure, as your primary residence serves as collateral.
- Account for ongoing ownership costs, including property taxes, home insurance, and loan fees.
Borrowers should carefully evaluate their specific financial situation before leveraging their property, remembering that lending terms, interest rates, and personal circumstances frequently change.
What to do: Prioritize traditional emergency savings before considering your property as a financial cushion. If you must tap into your equity, restrict the funds strictly to essential needs or high-interest debt elimination rather than lifestyle spending.
Source Money.com — money.com/dave-ramsey-home-equity-retirement/?xid=moneyrss ↗
Read next
 📈Investing Basics
Medicare Income Surcharge Tiers for 2027 Announced
Medicare's 2027 income surcharge tiers start at $112,000 for single retirees and $224,000 for couples, with the deciding tax return having been filed seven months ago. Ce…
🧾TaxesIRS Raises Annual Gift Tax Exclusion to $20,000 for 2027
The Internal Revenue Service has increased the annual gift tax exclusion to $20,000 per recipient for the year 2027, allowing individuals and couples to transfer larger s…
 📒Budgeting & Saving
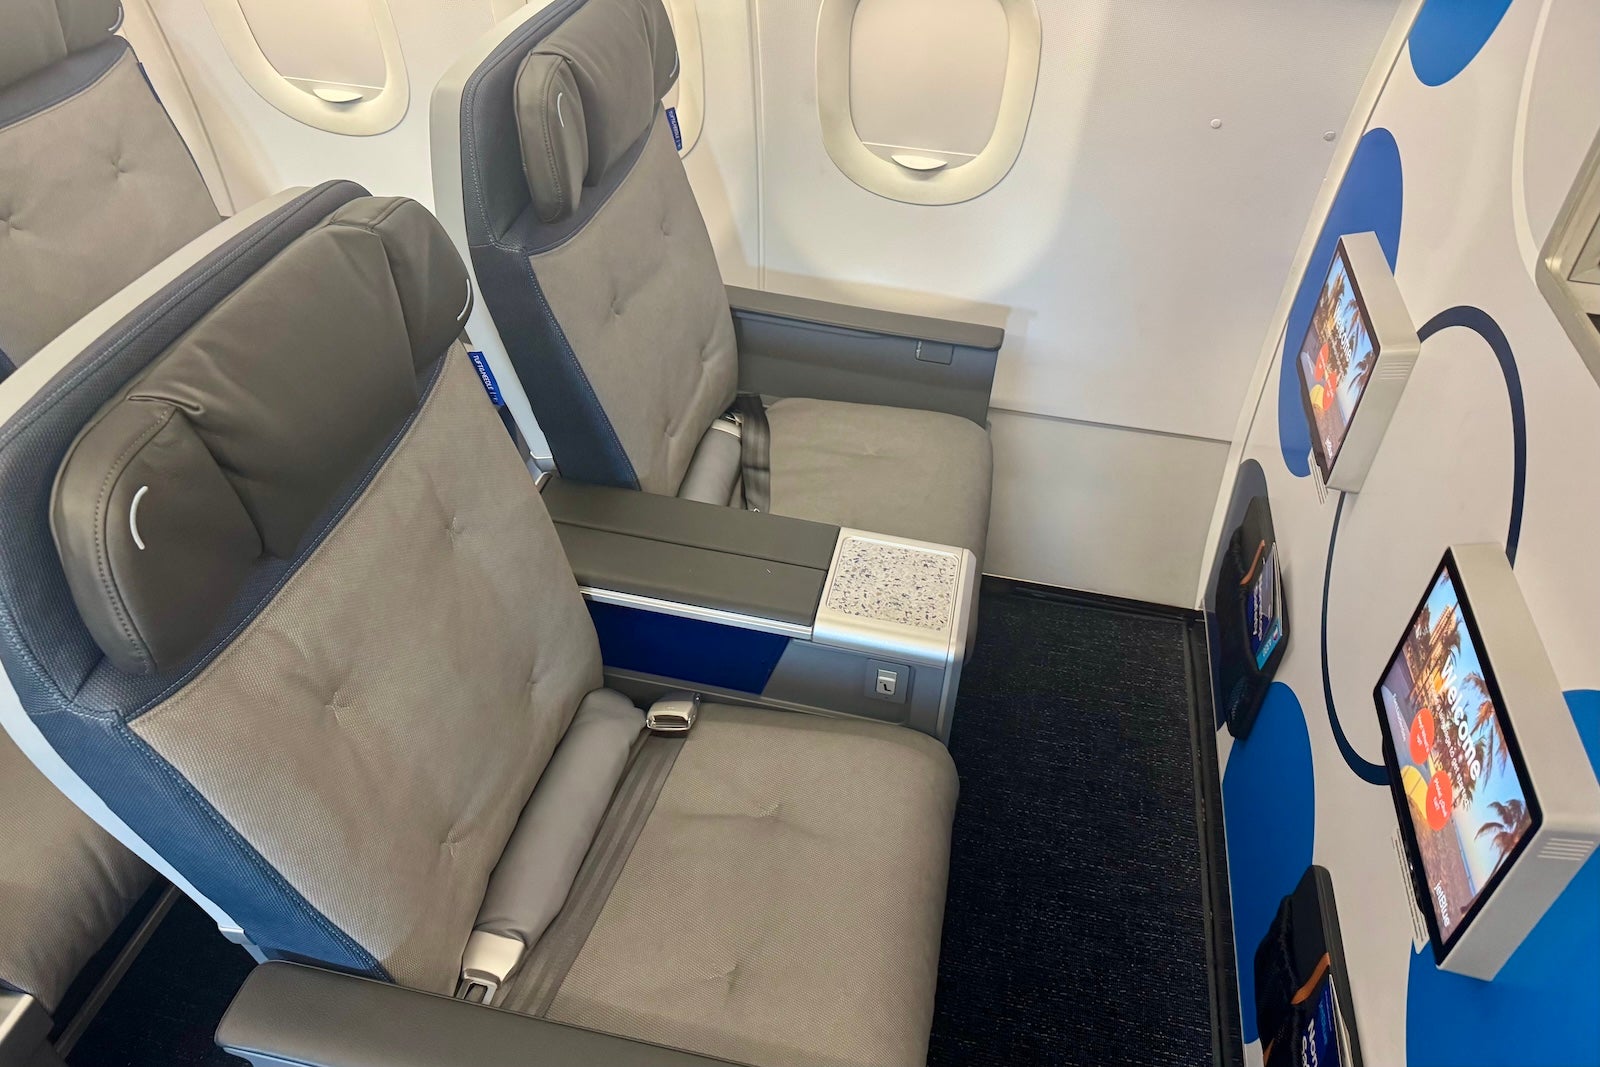
JetBlue Unveils New 'BlueFirst' Seating and Elite Upgrade Perks
JetBlue is launching a domestic first-class product called BlueFirst, bringing new seating options, chilled bento box meals, and complimentary upgrade perks for elite loy…
 🧾Taxes
Navigating the 1099 Shift: Tax Strategies for Independent Professionals
Transitioning to independent contractor status requires professionals to manage their own tax withholdings, business structures, and financial recordkeeping to avoid IRS …
 📒Budgeting & Saving
Kroger and Harris Teeter Launch 4x Fuel Points Promotion on Gift Cards
Shoppers at Kroger and Harris Teeter can earn quadruple fuel points on third-party and fixed-value Visa or Mastercard gift cards through December 1, 2026.
 💳Credit Cards & Credit
Understanding American Airlines AAdvantage Elite Status and Loyalty Points
American Airlines utilizes a Loyalty Points system for its AAdvantage program, allowing frequent flyers to secure elite status through everyday spending, partner purchase…