Why Working Past 65 Changes Your Social Security and Medicare Strategy
Reaching age 65 brings Medicare eligibility, but claiming Social Security too early while still employed can result in withheld benefits and lower lifetime payments.
 📈Investing Basics
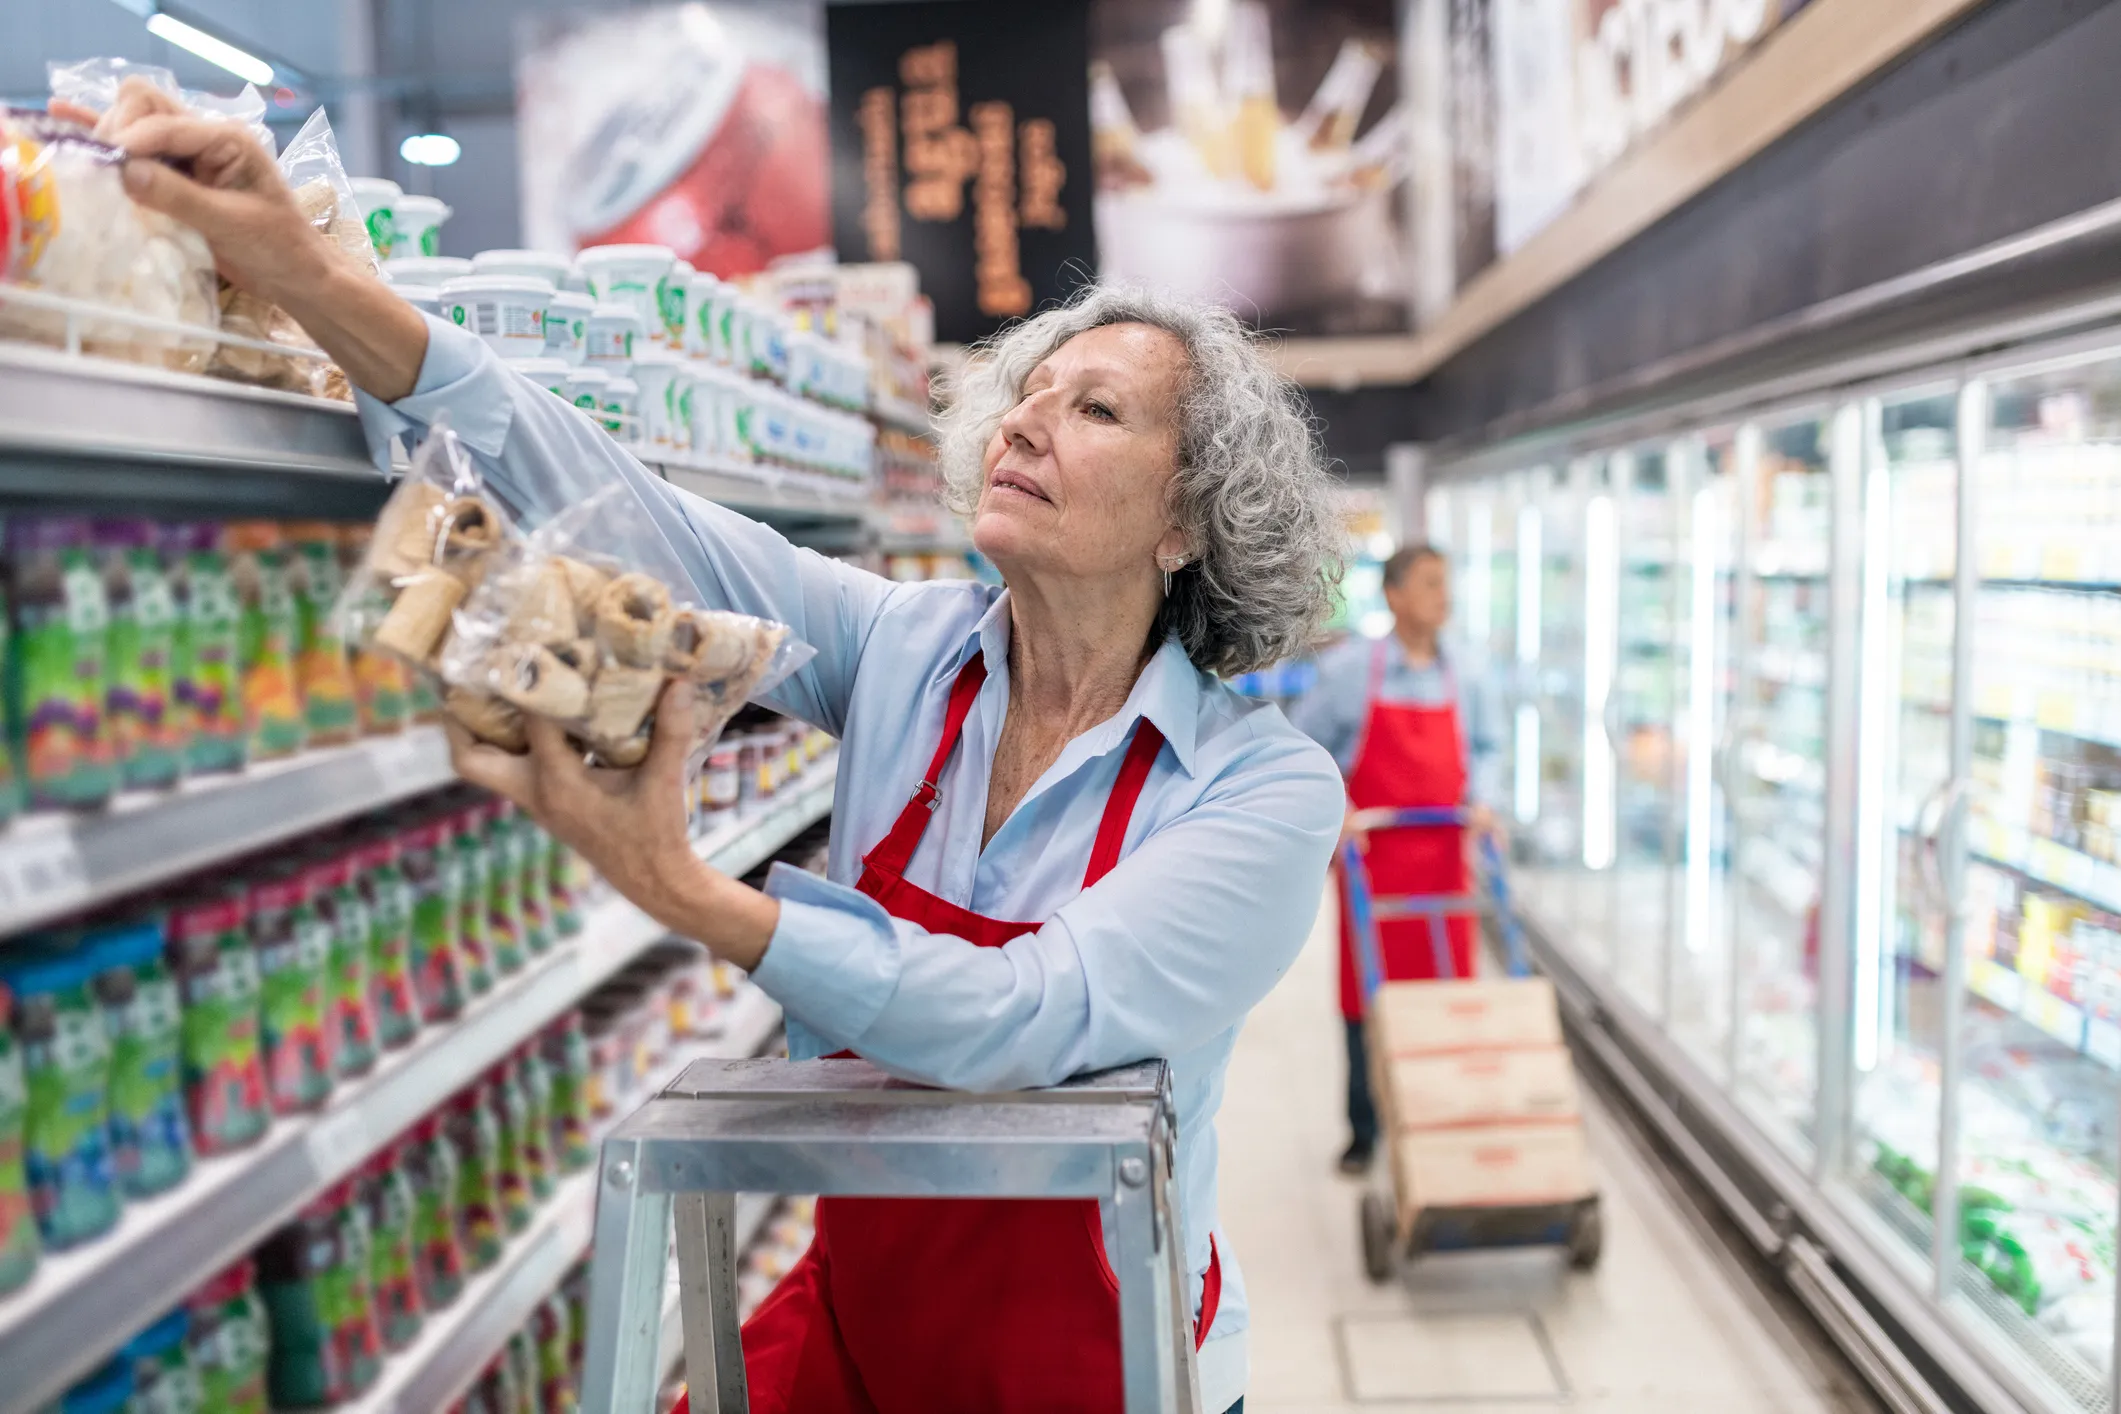
Photo: Money.com
Key points
- Full retirement age is 67 for those born in 1960 or later, meaning claims at age 65 while working face benefit withholding.
- The earnings limit for withholding is $24,480 in 2026 for workers under full retirement age.
- Delaying Social Security up to age 70 allows workers to build delayed retirement credits and secure higher lifetime payouts.
Reaching age 65 is a major milestone for older adults, often triggering thoughts of retirement alongside eligibility for Medicare. However, for those who continue working past this age, coordinating Social Security benefits requires careful planning. Because full retirement age is 67 for individuals born in 1960 or later, claiming benefits at 65 while earning a steady salary can lead to reduced monthly payments due to government withholding thresholds.
For individuals below full retirement age, Social Security withholds $1 of benefits for every $2 earned above the predetermined income limit, which is set at $24,480 for 2026. For example, a worker expecting a $2,000 monthly benefit could see those payments significantly reduced if their salary exceeds the threshold. In the year you reach full retirement age, the rules ease slightly, withholding $1 for every $3 above a higher limit of $65,160 in 2026. While withheld money is not permanently lost—the administration recalculates benefits later to provide credits—immediate cash flow can take a substantial hit.
Continuing to work past 65 also presents an opportunity to boost lifetime earnings and maximize retirement income. Delaying benefits allows workers to accumulate delayed retirement credits up until age 70, potentially increasing the eventual payout. Furthermore, higher earners should weigh how additional wage income affects the taxability of their benefits and factor in spousal survival benefits, which are typically based on the higher earner's record.
What to Watch
- Review official Social Security benefit calculators to estimate how continued employment affects your payouts.
- Monitor employer health coverage rules to avoid late enrollment penalties when coordinating with Medicare Part B at age 65.
- Assess whether your current salary can comfortably cover living expenses without needing to tap into Social Security early.
Note: Rules and earnings limits are subject to change. This overview is for informational purposes and does not constitute formal financial or tax advice.
Source Money.com — money.com/working-at-65-social-security/?xid=moneyrss ↗
Read next
 🏠Mortgages & Housing
Mortgage Rates Hold Steady at 7.01% Following Veterans Day
Average 30-year fixed mortgage rates remained at 7.01% following the Veterans Day holiday as the market digests recent inflation data and Treasury yield shifts.
 🧾Taxes
IRS Raises Annual Gift Tax Exclusion to $20,000 for 2027
The Internal Revenue Service has increased the annual gift tax exclusion to $20,000 per recipient for the year 2027, allowing individuals and couples to transfer larger s…
 📒Budgeting & Saving
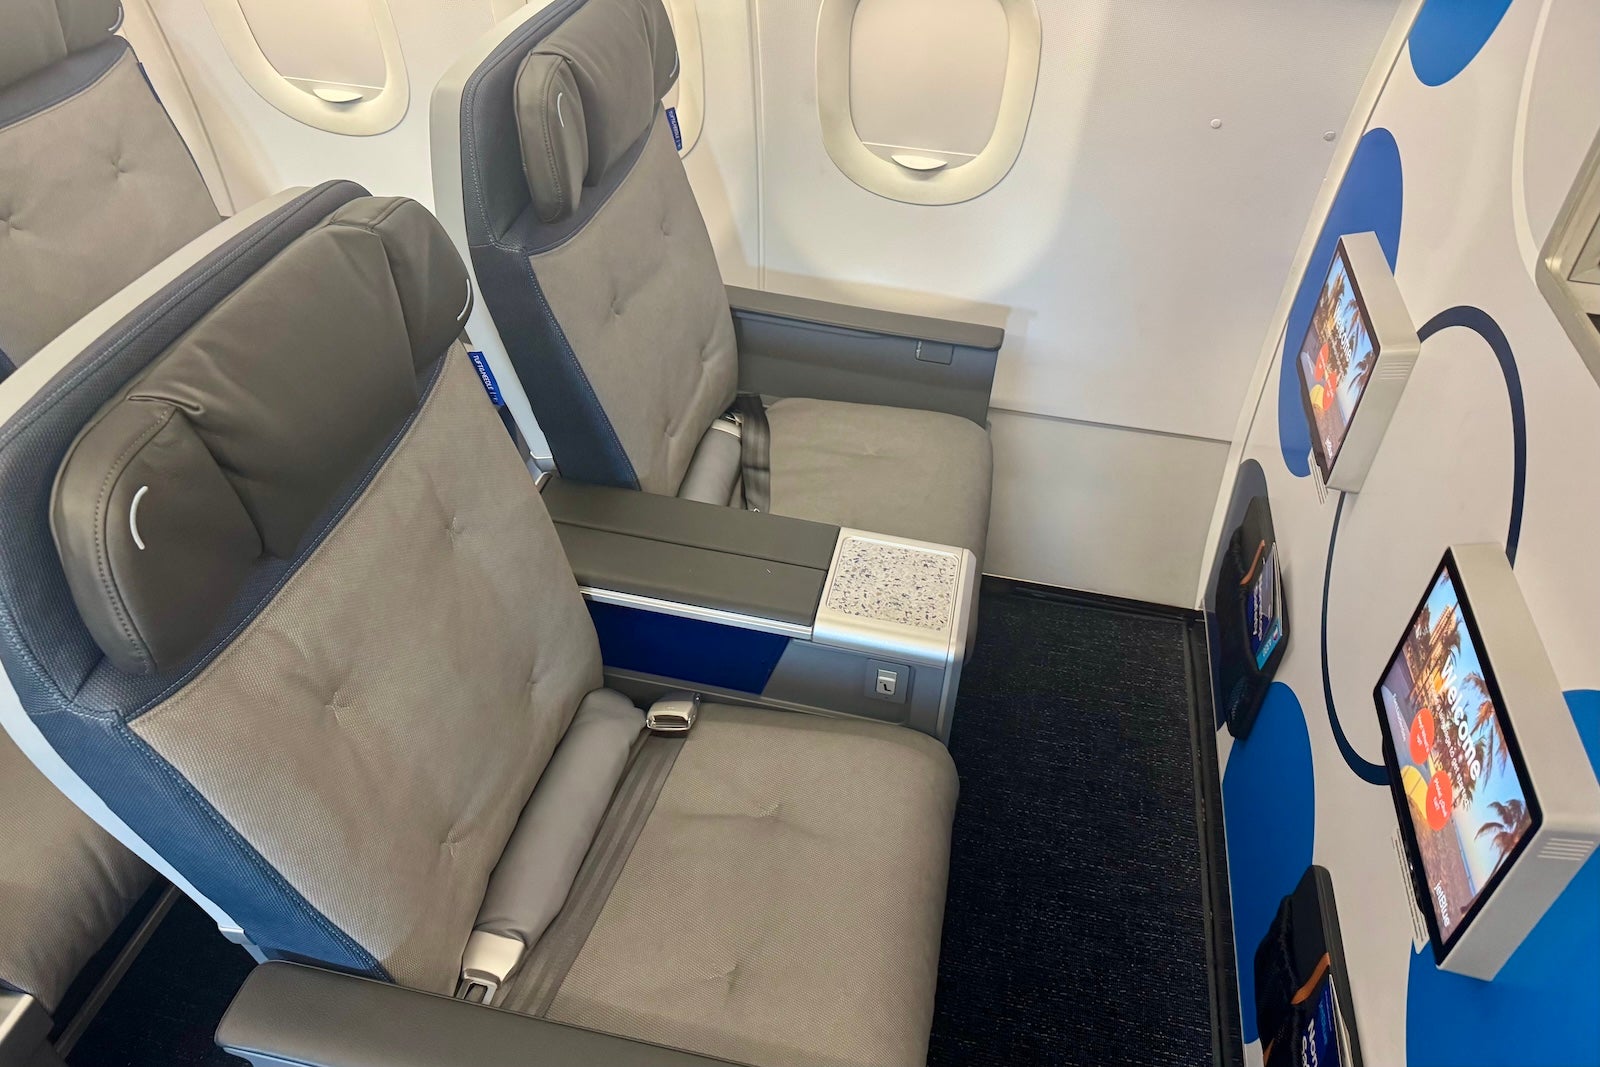
JetBlue Unveils New 'BlueFirst' Seating and Elite Upgrade Perks
JetBlue is launching a domestic first-class product called BlueFirst, bringing new seating options, chilled bento box meals, and complimentary upgrade perks for elite loy…
 🧾Taxes
Navigating the 1099 Shift: Tax Strategies for Independent Professionals
Transitioning to independent contractor status requires professionals to manage their own tax withholdings, business structures, and financial recordkeeping to avoid IRS …
 📒Budgeting & Saving
Kroger and Harris Teeter Launch 4x Fuel Points Promotion on Gift Cards
Shoppers at Kroger and Harris Teeter can earn quadruple fuel points on third-party and fixed-value Visa or Mastercard gift cards through December 1, 2026.
 💳Credit Cards & Credit
Understanding American Airlines AAdvantage Elite Status and Loyalty Points
American Airlines utilizes a Loyalty Points system for its AAdvantage program, allowing frequent flyers to secure elite status through everyday spending, partner purchase…